Does Insurance Cover ADHD Testing?
BetterHelp insurance availability, coverage, and cost may vary by state, plan, provider network, therapist availability, and deductible status.
Yes, many insurance plans cover some forms of attention-deficit/hyperactivity disorder (ADHD) testing, though how much they cover depends on your specific plan, the provider you see, and the type of evaluation you receive.
For example, many heath plans may cover some or most of the cost of a basic ADHD diagnostic evaluation, while coverage for comprehensive neuropsychological testing can be more difficult. Costs may also vary depending on whether your provider is in-network or out-of-network.
Knowing what affects your insurance coverage for ADHD testing, the typical costs, and what an evaluation involves may help you take the next step with more confidence.
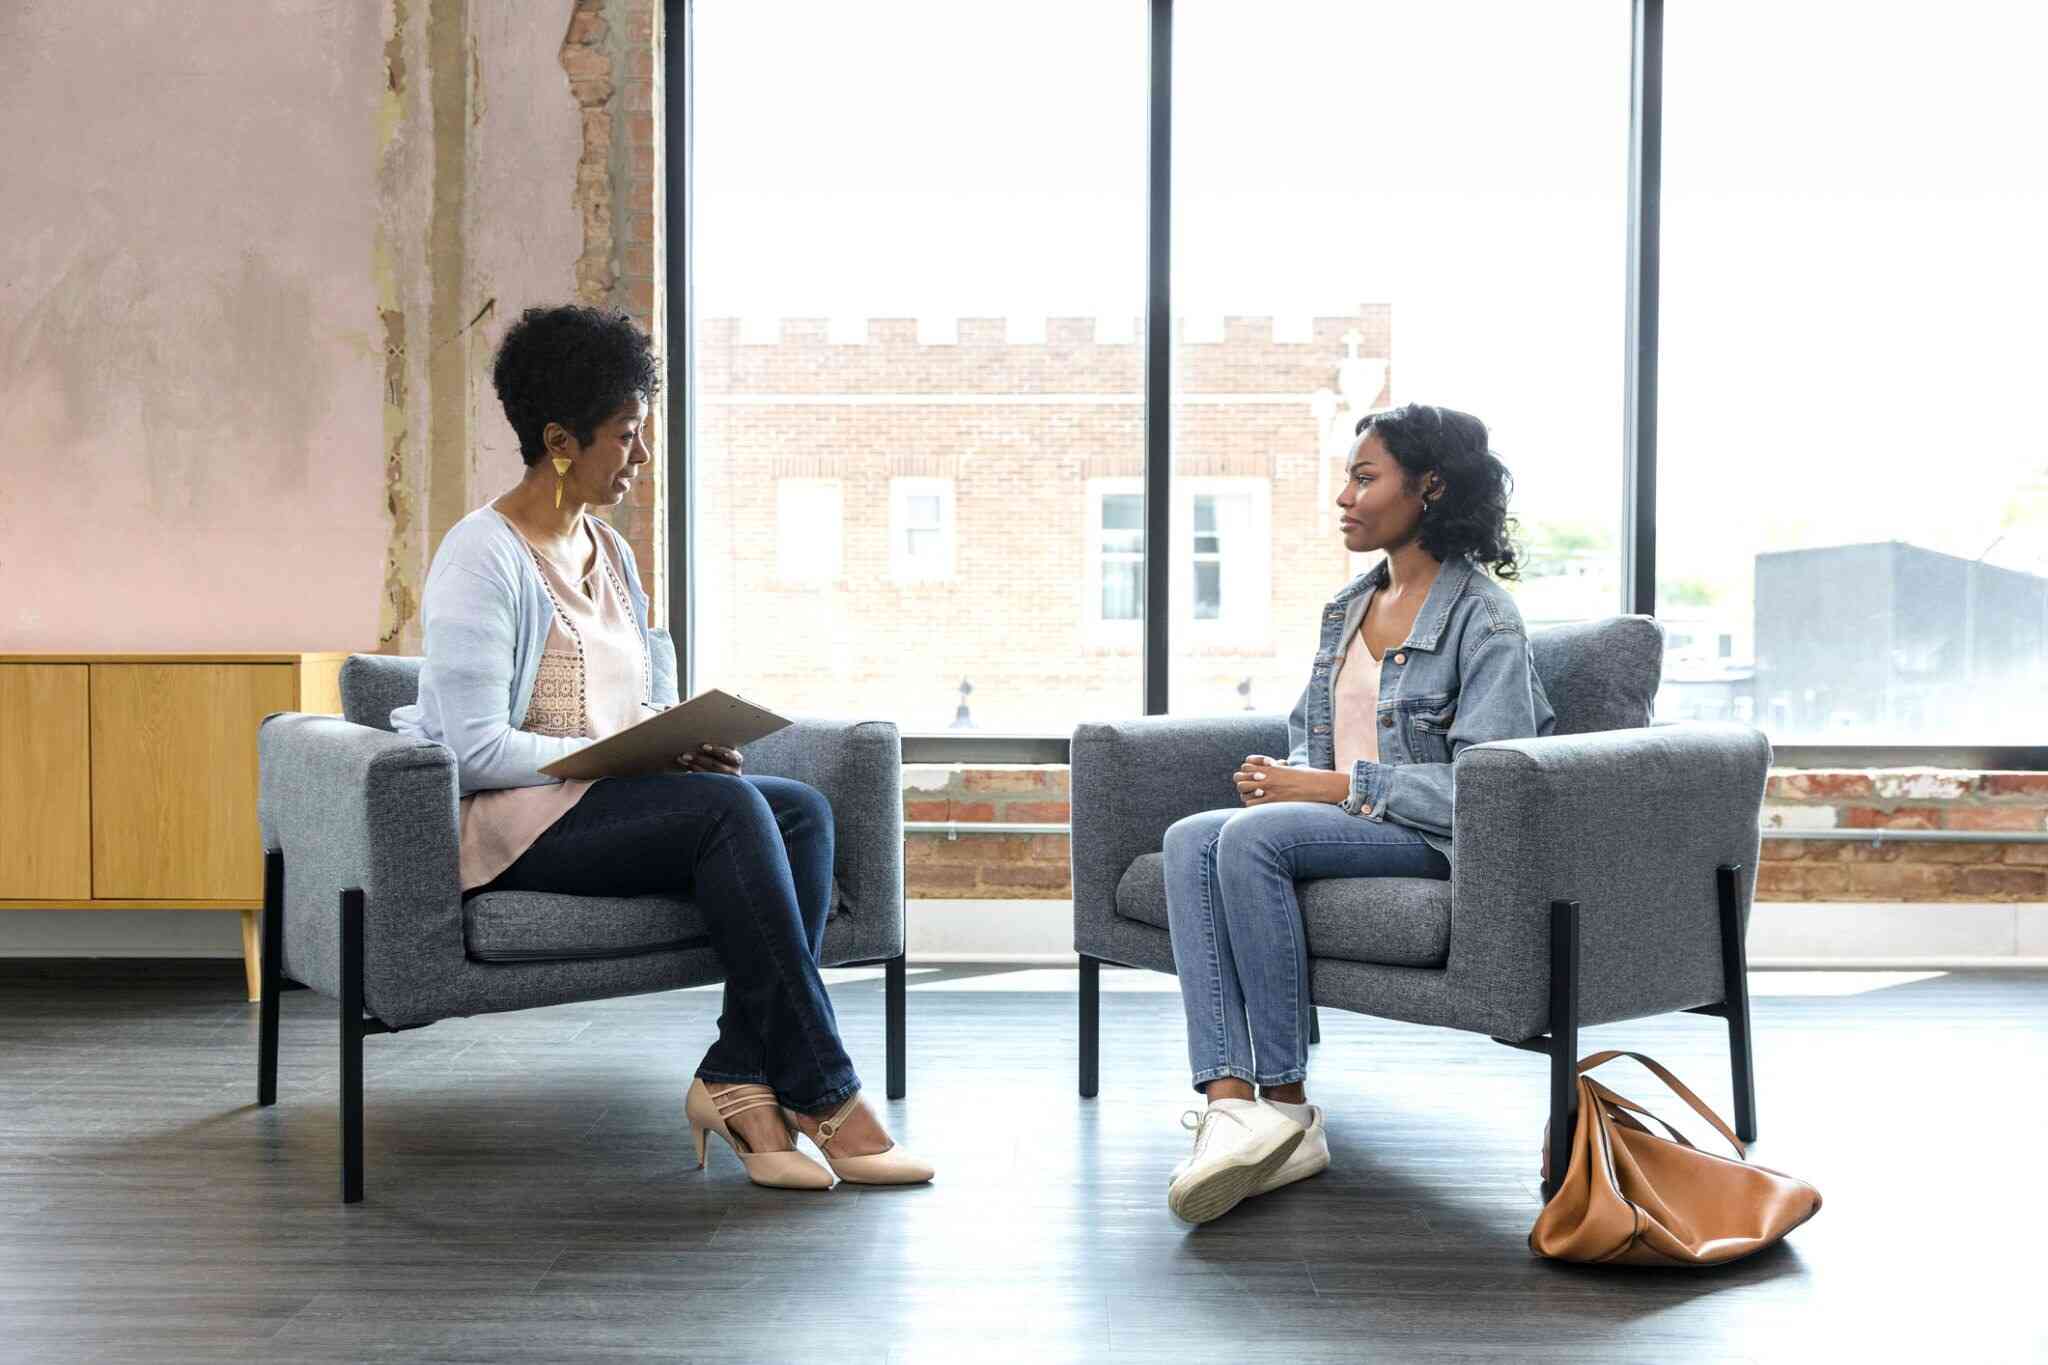
Table of Contents
- Does Insurance Cover ADHD Testing?
- How Much Does ADHD Testing Cost?
- What Does An ADHD Evaluation Include?
- Does Insurance Cover ADHD Testing For Adults?
- How Can Therapy Help After An ADHD Diagnosis?
Does insurance cover ADHD testing?
If you think you may have ADHD, one of your most immediate questions may be: is testing for ADHD covered by insurance? The answer isn’t as straightforward as a simple “yes” or “no” for a number of reasons, the first being that “ADHD testing” can mean a few different things.
There’s no single, standalone test for ADHD, so to understand whether insurance covers ADHD testing, it’s necessary to first clarify exactly what we mean by “testing.”
Two of the most common types of ADHD testing include:
ADHD diagnostic evaluation
In some cases, a primary care physician, psychiatrist, or other qualified healthcare provider may be able to conduct a basic ADHD diagnostic evaluation to provide an ADHD diagnosis. This is typically the quicker, more accessible option (often taking a couple of hours over one or two visits), but it may not be appropriate, possible, or sufficient in all situations. While some primary care providers may diagnose ADHD themselves, others may refer you to a specialist instead. This option typically relies mostly on a structured clinical interview and self-report rating scales.
Comprehensive neuropsychological testing
In this type of evaluation, you meet with a clinical psychologist or neuropsychologist for a clinical interview and extensive cognitive testing on areas such as attention, processing speed, language, executive function, and memory.
This option evaluates for many different conditions (not just ADHD), so it can be a more appropriate option if you think there may be other conditions present beyond ADHD. It often takes several hours across multiple sessions and results in a detailed, multi-page report. It’s important to note that this type of evaluation is often required for those seeking certain academic accommodations.
In terms of insurance coverage, generally speaking, an ADHD diagnostic evaluation is often covered by insurance, while comprehensive neuropsychological testing often isn’t, unless it’s considered “medically necessary,” which can be difficult to prove.
That said, insurance coverage isn't always all-or-nothing, and several different factors can affect it, even beyond the type of evaluation you’re seeking.
The same therapy you trust, with the option to use insurance
BetterHelp offers more ways to access online therapy, with insurance options available through providers participating in 125+ health plans. Insurance availability and coverage may vary by state, plan, provider network, therapist availability, and deductible status.
Get startedWhat affects ADHD testing coverage?
In addition to the type of evaluation you get, some of the other factors that can impact how much of your ADHD testing is covered include:
In-network vs. out-of-network: One of the biggest factors in what you'll pay is whether your provider is in-network or out-of-network with your plan. In-network providers have a contract with your insurance company, which usually means lower out-of-pocket costs for you. Out-of-network providers don't have that contract, so you may need to pay upfront and then request reimbursement from your insurer afterward. So, it’s worth confirming a provider's network status before booking.
Plan type: HMO, PPO, and other plan structures affect which providers you may see and how much you pay. An HMO may require referrals or limit you to a narrower network, while a PPO often offers more flexibility at a higher cost.
Deductible status: Some insurance plans may only cover some or all of the cost of testing after you’ve hit your deductible. Before hitting your deductible, you may be responsible for the full cost of the covered service yourself.
Medical necessity: Some insurers only approve coverage when there is documentation showing the evaluation is medically necessary. Your provider may help supply the notes or documentation your plan requires.
Provider licensing: Coverage may depend on who conducts the evaluation. For instance, for an ADHD diagnostic evaluation, insurers often require that the testing be conducted by a licensed psychiatrist, family physician, or other qualified professional.
Knowing these factors ahead of time may help you avoid surprises. Because they vary so widely, one person may have their ADHD testing covered in full, while another with the same diagnosis pays much more. Checking your plan's specifics is the surest way to know where you stand.
To understand your coverage, you can ask your insurer questions such as:
- Is an ADHD diagnosis covered by insurance under my current plan?
- What exact evaluations and services are covered by my health insurance for ADHD testing? (It can be helpful to ask for specific CPT codes of covered services.
- What do I need to do first in order for those evaluations and services to be covered? (For example, you may need to get a referral from your primary care provider or prior authorization from the insurer.)
- Which providers are in-network for my plan?
- Do I need to hit my deductible before these services are covered?
1.7M reviews with a 4.9/5 ★ session rating
Find the right therapist for you.
What type of therapy are you looking for?
Let's walk through the process of finding the right therapist for you! We'll start off with some basic questions.
How much does ADHD testing cost?
If you have health insurance, the cost of ADHD testing will largely depend on how much of the evaluation (if any) your insurance plan will cover. Let’s take a look at possible costs for the two most common types of evaluations:
For a diagnostic ADHD evaluation, the cost is often the cost of seeing a specialist under your plan. If you’re seeing an in-network specialist, this could be just a flat copay for the visit (often around $45), or the full allowable amount for the visit if you haven’t met your deductible, depending on your plan.
For comprehensive neuropsychological testing, some insurers may cover some part of the evaluation if it’s deemed medically necessary (as noted earlier), but this can be difficult. Typically, these evaluations can cost around $1,200 to $3,000.
Because the range is so wide, it can be important to contact your insurer to understand the details of your particular plan and how it treats the type of ADHD testing you want to pursue. A quick conversation upfront may save you from an unexpected bill later.
How much does ADHD testing cost without insurance?
Without insurance, the cost of ADHD testing is a different story. For a diagnostic ADHD evaluation with a psychiatrist without insurance, the cost might be several hundred dollars. And for comprehensive neuropsychological testing, the typical cost of around $1,200 to $3,000 would be entirely the patient’s responsibility.
Cost is one of the most common reasons people put off getting mental health services: according to BetterHelp research, 52% of Americans who aren't seeking mental health care point to cost as a barrier. If the high cost of testing is standing in your way, know that you’re not alone and that there are options available that can help make ADHD testing more affordable.
Below are a few possible ways to lower the cost of ADHD testing:
Ask a provider whether they offer sliding-scale fees based on income, payment plans that spread the cost over time, or a reduced rate for self-paying clients.
Look into university programs in clinical psychology or medical schools that may offer free or low-cost clinics, where graduate students may perform evaluations under close supervision from experts.
Consider using HSA/FSA funds to pay for testing, as it is typically considered an eligible medical expense.
What does an ADHD evaluation include?
Because ADHD shows up differently from person to person, thorough ADHD assessments usually pull together several pieces to build a complete picture. A comprehensive evaluation often includes:
- Clinical interview: A provider talks with you about your history, daily habits, and challenges to understand how symptoms affect your life.
- Standardized questionnaires: These rating scales help measure ADHD symptoms consistently and compare them against typical benchmarks.
- Input from family members or teachers: Observations from people who know you well may reveal patterns across different settings, like home, work, or school.
Meanwhile, comprehensive neuropsychological testing may include these elements as well as an extensive series of cognitive tests. With both types of evaluations, there’s a reason it can be such a thorough process.
An ADHD evaluation isn't just about confirming a diagnosis; it's about ruling out other possible explanations. Anxiety, sleep issues, and even everyday stress can look a lot like ADHD on the surface. Taking the time to sort through that is what leads to support that actually fits.
If you receive an ADHD diagnosis, treatment might include a mix of approaches, such as medication management, behavioral strategies, and in-person or online therapy. A thorough assessment can help inform what types of treatment may be most effective.
Does insurance cover ADHD testing for adults?
Adults often wonder whether health insurance covers ADHD testing differently than for children. Most insurance plans cover adult ADHD evaluations much like they do for children, though some insurers apply different requirements or documentation standards for adults.
That said, adults may face a few extra hurdles worth planning around. Because ADHD was long thought of as a condition that could only affect children, there might be fewer specialists who focus on adult testing, which sometimes means longer waitlists for an appointment.
If you're an adult seeking an ADHD evaluation, it helps to start early. Ask your insurer for a list of in-network providers, and get on a schedule sooner rather than later. A little planning ahead may spare you frustration and get you to answers faster.
How can therapy help after an ADHD diagnosis?
Getting an ADHD diagnosis may bring relief but also raise a lot of new questions. Once you know what you're working with, the next step is figuring out how to manage day-to-day life in a way that works for you. This is where therapy may play a meaningful role in helping you turn a diagnosis into a practical plan.
Many people navigating a new ADHD diagnosis find it helpful to talk with a licensed therapist about coping strategies and daily routines. A therapist may work with you to build tailored interventions for the challenges that come up most, whether that's staying organized, managing time, or handling the emotions that may come with ADHD.
With an online platform like BetterHelp, you can connect with a therapist from the comfort of home and reach out through in-app messaging between sessions when questions pop up. That flexibility may make support easier to fit into an already full schedule.
Note that BetterHelp doesn't offer ADHD testing or diagnostic evaluations. Instead, many providers on BetterHelp may offer therapeutic support once you have a diagnosis. BetterHelp accepts insurance through many major insurance plans, and eligible members’ average copay is $23 per session. Insurance availability and coverage may vary by state, plan, provider network, therapist availability, and deductible status.
In-Person Therapy
$100–$350 / session
BetterHelp Out of Pocket
$70–$100/week**
*Insurance availability, coverage, and cost may vary by state, plan, provider network, therapist availability, and deductible status.
**Subscription pricing is based on factors such as your location, referral source, preferences, therapist availability and any applicable discounts or promotions that might apply.
Moving forward with confidence
Figuring out whether insurance covers ADHD testing may feel like one more hurdle when you're already juggling a lot. Coverage depends on your specific plan, so a quick call to your insurer is the surest way to know what to expect before you schedule an evaluation. Whatever you find, support is available at every step, from the evaluation itself to the care that comes after.
Takeaway
How much does ADHD testing cost with insurance?
With insurance, the cost of ADHD testing could be anywhere from around $45 to $3,000 or more, depending on your insurance plan, the type of evaluation you’re getting, and the provider.
How much does ADHD testing cost without insurance?
Without insurance, the cost of ADHD testing often ranges from several hundred dollars to $3,000 or more, depending on the type of evaluation, the provider, and your location.
Does Medicaid cover ADHD testing for adults?
Medicaid coverage varies by state, and states are required to cover only certain mental health services, such as medically necessary inpatient and outpatient hospital services, home health services, and physician services; however, each state defines medical necessity in its state plan. To determine Medicaid coverage for your situation, contact your state’s Medicaid program for details.
Does insurance cover ADHD testing?
Many major insurance plans offer partial or full coverage for ADHD testing, though the exact amount depends on the plan. Coverage may also vary based on whether the provider is in network and whether the evaluation is considered medically necessary. Checking directly with your insurer is the most reliable way to confirm your specific benefits.
Does health insurance cover ADHD testing for adults?
Many insurance plans cover ADHD evaluations for adults, similar to coverage offered for children. Some insurers may have different documentation requirements or provider networks for adult testing. It's worth confirming details with your plan before scheduling an evaluation.
Is an ADHD evaluation expensive without insurance?
A comprehensive ADHD evaluation may be a significant expense when paid out of pocket, since it often involves several components like interviews and questionnaires. Costs vary widely depending on the provider and location. Some providers offer sliding scale fees or payment plans, so it may help to ask directly.
Does BetterHelp provide ADHD testing?
No, BetterHelp does not currently offer ADHD testing or diagnostic evaluations. Many providers on BetterHelp now accept major insurance carriers and may offer therapeutic support once a diagnosis has been made, such as help with coping strategies and daily routines.
Do all insurance plans require preauthorization for ADHD testing?
Not all plans require preauthorization, but some do, depending on the insurer and plan type. This is typically outlined in your plan's mental health or behavioral health benefits section. Contacting your insurer ahead of time may help you avoid unexpected costs.
- Previous Article
- Next Article
This article provides general information and does not constitute medical or therapeutic advice. Mentions of diagnoses or therapy/treatment options are educational and do not indicate availability through BetterHelp in your country.
BetterHelp insurance availability, coverage, and cost may vary by state, plan, provider network, therapist availability, and deductible status.